Contact Form

Name

Email *

Message *

Showing posts with label recession. Show all posts

Wednesday, June 27, 2018

Maybe He Should Avoid Politics, Predicting The Future And Stay With Being Funny!


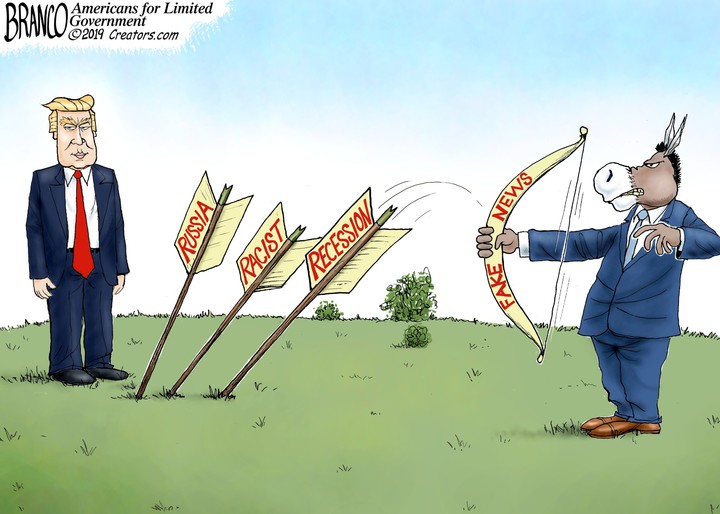
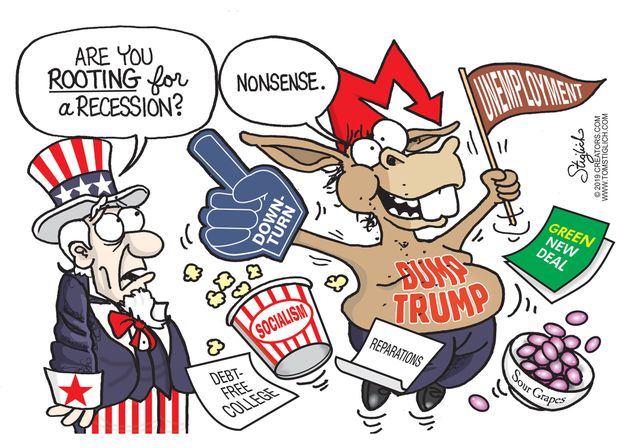
Maher Would Prefer A Recession Over Trump

HBO’s Bill Maher spoke about the issue caused by his previous comments that insisted a recession would be worth it if it undermined Trump’s popularity. He stated his critics should “take a course in perspective.” Adding, “A recession is a survivable event, what Trump is doing to this country is not.”
Maher stated, “[A]nyone who went apeshit in the last two weeks because I said going through a recession would be worth it if it undermined Trump’s popularity has to enroll in college and take a course in perspective. A recession is a survivable event, what Trump is doing to this country is not. Democracy is about to go the way of the dinosaurs because we’ve been taken over by a dodo bird.”
“Another recession is coming, not because I’m rooting for it, because someone passed a giant tax giveaway to the rich that added trillions to the debt and started a trade war for no reason and deliberately sabotaged the Affordable Care Act and rolled back the rules for banks so they can once again gamble with our money. Those are actual policies, from men with real power, as opposed to me, who just made a wish.”

Wednesday, December 27, 2017

A Trump Opponent Starts Figuring Out Trump

What I got wrong about Trump in 2017

Rick Newman
Columnist


Ad: 6 seconds
When Donald Trump won the 2016 presidential election, I predicted gloom. “The policies he favors … pose many land mines for the economy,” I wrote the day after the election. The result, I suggested, could be a prompt Trump recession.
There was no Trump recession. Quite the contrary, in fact. Economic growth accelerated modestly in 2017. Job growth has continued to improve steadily. The biggest financial story in 2017 is the stock market, with the S&P 500 index up a robust 20% for the year. Americans feel increasingly confident about their prospects, and the business tax cuts Congress just passedought to keep the party going.
How did I get this so wrong?
Many critics have weighed in via email and Twitter, arguing that I’m a fake-news practitioner biased against Trump. They’re wrong. It’s true that I’m turned off by Trump’s bombast, by his untruths, and by his racially charged incitements. But I also concede that Trump won legitimately in 2016, in large part because he understood the frustrations of millions of disaffected voters his many opponents in both parties talked down to or simply ignored. Voters wanted change. Trump delivered it.
Here’s why I guessed wrong about Trump’s impact on the economy: I expected him to do what he said he would do. Instead, Trump has done only some of what he said he would do, and apparently accepted the counsel of cooler heads persuading him to deep-six several of his most troubling campaign promises. People who know Trump say it’s a mistake to take everything he says literally. Instead, they advise, follow the direction of his thinking, while leaving considerable room for detours. This is the lesson I hope to take from 2017.
As a candidate, Trump promised several things that would almost certainly harm the economy if put into action:
  • Tough new limits on trade with China, including new tariffs on imports as high as 45%
  • Canceling the North American Free Trade Agreement if the United States doesn’t get more favorable terms, and imposing tariffs in the range of 35% on imports from Mexico and some other countries
  • Expelling all 11.3 million undocumented immigrants in the United States, and putting tough new limits on legal immigration
  • Overhauling the Federal Reserve
On three of those four issues, Trump has done nothing (yet). As a candidate, he bashed the Fed and denigrated Chair Janet Yellen, whom investors thoroughly respect for her careful leadership of one of the world’s most powerful institutions. As president, however, Trump became a quick convert to Yellen’s style of handling the economy. And his choice to succeed her, Jerome Powell, is a Yellenite whom markets like because he seems unlikely to rock the boat at the Fed.
On trade, Trump’s minions are, in fact, working behind the scenes to revamp NAFTA and the U.S. trade relationship with China. But so far, Trump has declined several opportunities to take tough steps that might disrupt the status quo.
FILE – In this Nov. 9, 2017, file photo, President Donald Trump and Chinese President Xi Jinping participate in a welcome ceremony at the Great Hall of the People in Beijing, China. (AP Photo/Andrew Harnik, File)
On immigration, Trump has in fact cracked down, to some extent, on undocumented migrants and imposed some new limits on legal immigration. But even this hasn’t been the Gestapo-like crusade some economists and business leaders feared.
Meanwhile, Trump has delivered the one thing companies love most: tax cuts.
As the 2016 election neared, several well-known research groups—including Moody’s Analytics, Citibank, Oxford Economics and Macroeconomic Advisers—estimated the impact Trump’s policies would have on the economy. They examined all of his policies, not just the salubrious ones. And all of them saw trouble—declining growth, falling stock values, rising unemployment, and a possible or likely recession. Those analyses, based on Trump’s full set of campaign promises, prompted gloomy stories like the one I wrote right after the election.
Trump fooled us in 2017. He only pursued policies likely to be good for the economy, while setting aside those that most troubled economists and business owners. Will he do the same in 2018? Let’s hope so. Trade wars would still raise prices, kill jobs and hurt workers. And the economy arguably needs more legal immigrants, not fewer, to help fill the 6 million job openings employers can’t fill and crank up production even more.
Trump clearly revels in the frothy stock market, tweeting frequently about how his policies are driving stocks to one record high after another. Maybe he’ll quit while he’s ahead, and find a way to declare victory on trade and immigration without changing much. Some campaign promises are best left unfulfilled. And some predictions are subject to revision.

Wednesday, January 4, 2017

Will This Be Trump's Recession?


The false economic recovery narrative will die in 2017


Yes, the narrative of the “new normal” has been around for so long now that many people have simply grown used to it. The assumption is that the fiscal “new normal” has become the fiscal “normal,” and though the fundamentals continue to strain under the weight of poor global demand and historic debt levitated by extraneous fiat stimulus, the masses feel far less fear than is warranted. Hey, why should they? We’ve managed around eight years skating on thin ice, why shouldn’t we expect eight more years of the same?
The banking elites have done the job they set out to do, which was to drive the economy to the very edge of the financial cliff, and then keep it suspended there until the general public became comfortable living next door to the abyss.
Why do this? Well, the greater dynamic at play here is something the average person will not understand or refuses to examine — economics today is about mass psychology. The economy is a tool, or a weapon, by which international financiers can influence the public mind and the emotions of the mob. In order to grasp the mechanics of economics it is not enough to deal in statistics and trade principles; one must also grasp human behavior and how it is manipulated. One must acknowledge that in economics we witness the transmutation of societies by word and by force, by chaos and by order. Economics is alchemy.
The globalists (in their twisted view) seek to change lead into gold, and just as in alchemy, these elements are a metaphor for psychological evolution. For the globalists, social engineering is a form of witchcraft; they see it as creation, or a grand form of architecture.
But it is not creation. The globalists are incapable of such art because true art requires wisdom and empathy. All they know is how to deconstruct existing systems generated by nature and free men and rearrange the left over pieces into something more oppressive and ultimately less interesting than what existed before. Give the internationalists a Mona Lisa and they will shred it, reconstitute it and regurgitate a paint by numbers coloring book.
The globalists only know how to turn gold into lead.
If you do not understand the reality of globalist influence in markets and the nature of economics as a weapon; if you actually believe that the economy operates purely on some kind of free-roaming free market principles, then you will never be able to wrap your head around the otherwise absurd behavior of our financial structure.
The psychology of fiscal “recovery” is a vital tool for change and for developing false dichotomies. For example, I recently came across this article from the pervasive propaganda hub of Bloomberg. In it, Bloomberg outlines a story we are by now very used to hearing from the mainstream — that the presidential era of Barack Obama has left the economy of the U.S. in particular in “far better shape” as he leaves office than when he entered office.
Now, anyone who has been reading my analysis for at least the past six months (if not the past ten years) knows exactly what I think about the current state of the economy and what is likely to happen in the near future. For those new to my position, here is a very quick summary along with linked evidence supporting my claims:
From the 1990’s leading into the year 2007, the Federal Reserve engineered a massive debt and derivatives bubble through the use of artificially low interest rates in the housing market. Alan Greenspan, the presiding Fed chairman at the time, openly admitted in interviews that the central bank knew an irrational bubble had formed, but claims they assumed the negative factors would “wash out.” This is a constant meme set forward by the Fed — that they were essentially too stupid to foresee a collapse of the bubble they knew they had created. They prefer that the public believes that the Fed was “incompetent” rather than deliberately destructive.
The low rates fueled a machine of mortgage backed securities and derivatives based on trillions of dollars in loans to people that had no ability or no intention of ever paying them back. The Fed had aid in this program from the ratings agencies, which labeled obviously toxic debt as AAA for years, and the SEC, which refused to investigate any legitimate claims of asset manipulation and ill intent. This corrupt behavior on the part of the SEC was showcased in the testimony of SEC whistle blower Gary J. Aguirre, who warned of dangerous debt pools and manipulation within the banking industry in 2006 before the derivatives collapse and also warned that the SEC interfered with any investigation attempts into the problem.
This led to the well known “Great Recession” triggered in 2007/2008. The Fed along with numerous other central banks around the world had conjured a crisis and then offered their own solution to that crisis. Namely, the solution of massive fiat stimulus programs purchasing toxic debt, treasury bonds, corporate stocks and anything else that wasn’t nailed down.
The “bailouts” and quantitative easing projects, however, were actually cover for a far larger program of untold trillions in overnight loans to corporations domestic and foreign.  A never-ending river of dollars created out of thin air and pumped into companies for near zero interest. It was these free overnight loans that allowed international conglomerates to purchase their own stocks through stock buybacks, thus reducing the number of existing stocks on the exchanges and artificially boosting the price of the remaining stocks. This caused stock markets to skyrocket from near death to historic highs.
In the meantime, government bureaucracy has worked tirelessly to manipulate statistics to falsely reflect an overall recovery. While some numbers slip through the cracks and issues of true supply and demand continue, the vast majority of the populace has little clue that the collapse of 2008 never actually stopped, it was just shifted into a state of slow motion.
The Fed’s low interest rates, specifically on overnight loans, has allowed the economy to sputter along for eight years, and has greatly enriched the top 1 percent in the process. But now, their strategy is changing.
The problem is that stimulus has a shelf life, and while certain stats can be misrepresented and the stock market can be inflated for a time, eventually, consequences must be accepted for attempting to defy gravity for so long.
The initial collapse was designed to foster an even greater event. Without the derivatives bubble, the central banks never could have convinced the masses to accept the idea of a fiat stimulus bubble which would eventually put the dollar at risk, along with the overall U.S economy. Taking the brunt of the 2008 crash would have been painful, but not insurmountable. But with eight more years and tens of trillions in added debt along with increased geopolitical tensions and an equities bubble for the ages, the scale of the final collapse will be truly unprecedented.
The purpose of this final event will be to generate so much chaos and desperation that the public will be compelled to search for extraordinary solutions. The globalists will be ready with those solutions, including those they have openly outlined decades in advance in publications like The Economist.
The end game? The formation of a single monetary and economic authority under the management of the International Monetary Fund, and the establishment of a single global currency using the IMF’s Special Drawing Rights as a “bridge” for locking national currencies into a harmonized exchange rate until they become pointless, interchangeable and replaceable.
The problem is, the globalists cannot possibly initiate this end game in a vacuum, otherwise, they would take the blame for the inevitable collateral damage to people’s lives as their “great global reset” is undertaken. The globalists need a scapegoat.
Enter Donald Trump, the Brexit Referendum, and the rise of “populist” movements. For the entire first half of 2016, globalists were “warning” non-stop that a rise in populism (conservatives and sovereignty champions) would result in international financial catastrophe. It was as if they knew that the Brexit would succeed and that Donald Trump would win the election…
This has been my position for the past half year — that globalists were planning to allow conservative and sovereignty movements to take the reigns of power, that they would allow the passage of the Brexit and the rise of Trump, just before they pull the plug on the system’s life support. The Federal Reserve in particular has already launched the final phase by beginning a series of rate hikes which will remove the safety net of free overnight loans to companies, thereby sabotaging equities markets. I specifically warned about this over a year ago when most analysts were stating that negative rates and QE4 were “just around the corner.”
And this is where we are today. As noted above, Bloomberg writes an interesting bit of propaganda starting with a bit of truth. Here’s the beginning quote from their article:
“Research suggests factors beyond the control of any U.S. president, not their actual policies, set the course of the economy. Yet with voters, President-Elect Donald Trump will secure much of the praise or blame when it comes to the impact of his agenda over the next four years.”
The recovery narrative from 2008 to today was imperative to the globalist’s greater agenda. For a considerable portion of the public must be made to believe that under a socialist and decidedly globalist president (Barack Obama) the general trend in the economy was positive and that “things were getting better.” This sets the stage for the final collapse and the IMF’s great reset, in which conservatives and sovereignty activists will be blamed, whether there is any evidence of culpability or not, for the crash that the globalists have spent the better part of two decades setting in motion.
After the dust has settled, the argument will be that the world was on course before the Brexit, before Trump and before populism. The argument will be that globalism was working and conservatives screwed it up with their selfish nationalist endeavors. After the final crash and perhaps numerous deaths from poverty and violence, the argument will be that the only conceivable solution must be a return to globalism in an extreme form; or total global centralization, so that such a tragedy will never happen again.
Bloomberg helps to set up the scenario, by claiming that Trump is “inheriting” a stable and improving economy compared to the economy that Barack Obama inherited:
“While today’s economy is a mixed bag by historical standards, one thing is clear: Obama has left Trump a 2016 economy in a better state, by many measures, than when he was first elected president in 2008 in the middle of the worst downturn since the Great Depression.”
Of course, Bloomberg fails to mention that the standards and statistics by which they measure economic “improvement” are entirely fraudulent.
For example, real GDP is at -2 percent, not +2 percent as Bloomberg claims, when one calculates for distortions such as government spending, which is counted towards GDP even though government does not actually produce anything. Government can only steal productivity from citizens and reassign that wealth elsewhere.
Bloomberg also cites a vastly improved unemployment rate. They once again refuse to bring up the fact that over 95 million Americans are no longer counted as unemployed by the Bureau of Labor Statistics because they have been jobless for so long they do not qualify to be included on the rolls. This lie of reduced unemployment has been pervasive through the entirety of the Obama Administration.
Bloomberg then mentions a greatly improved housing market that Trump will enjoy when he takes office. They certainly do not include the fact that pending home sales are now plummeting. And, they do not mention that the majority of the boost in home sales during Obama’s two terms was due to corporations like Blackstone buying up distressed mortgages and turning the homes into rentals. The housing market is not being supported by individuals and families seeking home ownership, but corporations snatching up real estate on the cheap and driving up prices.
And there you have it. The globalist setup continues with mainstream outlets telling Americans that the economy is in ascension as Trump and populists move into positions of power, when in truth the economy is as dire as it ever was if not worse off. The false recovery narrative will indeed die in 2017, and it will be because the globalists want it to die while nationalists are at the helm. This is perhaps the biggest con game in recent history; with conservatives as the fall guy and the rest of the public as the gullible mark. One can only hope that we can educate enough people on this scenario to make a difference before it is too late.
— Brandon Smith
Wednesday, October 19, 2016

More Bad News On The Economy. When People Don't Go Out To Eat Means They Don't Have The Money. Obama Recovery Is A Joke.

Restaurant Industry on Pace for Worst Year Since The Recession

 
At the current pace, 2016 would be the weakest annual performance since 2009, when the industry was recovering from the recession.
At the current pace, 2016 would be the weakest annual performance since 2009, when the industry was recovering from the recession. THINKSTOCK
The downturn for most of the restaurant industry continued during September. Same-store sales were negative for the fourth consecutive month and chain restaurants endured another period of declining guest counts. Even restaurant job growth, which until recently had been posting solid gains, dropped considerably. This insight comes from data reported by TDn2K through The Restaurant Industry Snapshot, based on weekly sales from nearly 25,000 restaurant units and 130-plus brands, representing $64 billion in annual revenue.
Same-store sales growth for September was down 1.1 percent, a decline of 0.5 percentage points from August. “The key driver behind the fall in sales during September was a decline in traffic, which continues to be the biggest challenge for chain restaurants,” says Victor Fernandez, executive director of insights and knowledge for TDn2K. “After improving slightly in August, traffic fell 3.5 percent in September. Traffic counts have fallen by at least 3 percent in four of the last six months.” 
The third quarter of 2016, at -1.0 percent same-store sales growth and -3.4 percent in traffic, was the weakest quarter since the second quarter of 2010. Year-to-date results also present a sobering picture. Through September, 2016 sales growth was -0.6 percent, driven by a troubling -2.8 percent change in traffic. At the current pace, 2016 would be the weakest annual performance since 2009, when the industry was recovering from the recession. 
Third quarter and 2016 results are, unquestionably, factors in the recent spate of organizational announcements. During the past few months, a number of bankruptcies have been reported, along with unit closures and executive changes. The industry continues to search for ways to revitalize traffic in an environment where general economic activity, including consumer sentiment, is relatively strong.
“The economy continues to expand at a pace that makes few happy,” says Joel Naroff, president of Naroff Economic Advisors and TDn2K economist. “Still, job gains remain reasonable and the main reason the unemployment rate has not declined is that growing confidence in the ability to find a job has brought more people into the labor force. That is a normal pattern, but it was delayed in this cycle. Wage gains continue to accelerate and this is leading to more spending on everything, especially food. Indeed, when all eating and drinking establishments are accounted for, retail sales for the sector were up 6.4 percent for the first eight months of the year. That is much faster than the 2.9 percent gain for all retailers. Growth in sales at restaurants has slowed recently, but only modestly according to the government’s numbers. There is no recession in the sector as households continue to eat out.”
While comp sales remain negative, new restaurant units continue to be added, albeit at a slower rate. No doubt some of this might be attributed to real estate deals that were in place prior to conditions slowing. But, the unit growth points out that some segments and brands are finding success navigating the market turbulence.
Quick service is an example. QSR was the top performer based on same-store sales in the third quarter with growth of 2.2 percent. All other segments were negative (except upscale casual, which was flat). Besides growing sales in existing restaurants, quick service (the largest segment in the industry based on sales) also posted the highest total sales growth during the first half of 2016, growing at a rate of 4.7 percent year-over-year.
The best performing region in the third quarter was California. It was the only region with positive sales in each quarter of 2016. California also had the largest absolute gain in year-over-year personal income for the second quarter, which likely translated into positive restaurant spending in recent months. The weakest region in the third quarter was again the Southwest, a distinction it has held for the last four quarters. Income growth seems to be a factor here as well. Of the four states included in this region, three (New Mexico, Louisiana and Oklahoma) are among the 10 states with lowest personal income year-over-year growth rate during the second quarter.
After growing at an average 3.7 percent year-over-year during the first seven months of the year, the creation of new chain restaurant jobs has slowed down since July. The growth rate for August was a modest 0.7 percent, according to TDn2K’s People Report. Even if this may alleviate some of the staffing pressures for restaurants, turnover rates for both hourly employees and restaurant management positions increased again during August. The industry has been experiencing an upward trend in its turnover rates for the last five years. Restaurant management turnover is now higher than it was before the recession for all industry segments and employee retention has been cited by most restaurant operators as one of their most critical challenges for 2016.
The People Report Workforce Index for fourth quarter predicts continued staffing and retention difficulties for the industry. Combined with the declining sales growth for many brands and segments of the industry, significant challenges are expected through the end of the year.
News and information presented in this release has not been corroborated by FSR, Food News Media, or Journalistic, Inc.

Wednesday, August 19, 2015

When Is The Next Recession Coming?

Bernanke to WSJ: US Unprepared for Next Recession

Image: Bernanke to WSJ: US Unprepared for Next Recession
By Dan Weil   |   
Historically, the U.S. economy suffers a recession every five to eight years, so given that our recovery is more than six years old, we may face a downturn soon.

And with monetary policy already in heavy-easing mode and fiscal policy hamstrung by the government's massive debt burden, the government's tools to combat any downturn are limited.

"As the U.S. economic expansion ages and clouds gather overseas, policy makers worry about recession," write Wall Street Journal reporters Jon Hilsenrath and Nick Timiraos. 


"Their concern isn’t that a downturn is imminent, but whether they will have firepower to fight back when one does arrive."

Former Fed Chairman Ben Bernanke is concerned too, though he's not panicking. The government's weapons to fight the next recession will be “more limited than usual, but they’re not zero by any means,” he told the paper.

The Federal Reserve's target rate for federal funds now stands at a record low of zero to 0.25 percent. And while the central bank is expected to start raising rates soon, many economists expect the rate to top out at 2 percent, and not until late 2016 or 2017.

On the fiscal side, federal government debt has soared to 74 percent of GDP from 39 percent in 2008. That leaves little room for higher spending and/or lower taxes.

Latest News Update

"We have very little cushion for whoever the next president is and the next congressional leaders if they had to deal, gosh, with anything," Glenn Hubbard, dean of the Columbia Business School and an adviser to President George W. Bush, told The Journal.

Meanwhile, when it comes to the world economy, Ambrose Evans-Pritchard, international business editor of The (London) Telegraph, says leading indicators and money supply data indicate growth will rise in the months ahead, at least in the United States, Europe and China, says.

He cites research from Gabriel Stein of Oxford Economics showing that real global M3 money supply growth — based on the United States, China, The European Economic and Monetary Union, the United Kingdom, Japan and Canada — soared to a six-year high of 6.2 percent in June.


"The M3 gauge tends to lead economic growth by 12 months or so, suggesting that the worst may soon be over," Evans-Pritchard writes.

Related Stories:
© 2015 Newsmax Finance. All rights reserved.